 Written by
Nylon Market to Reach USD 94.56 Billion by 2034, Driven by Automotive Lightweighting and Sustainable Material Innovations
Nylon Market Estimation and Growth Drivers
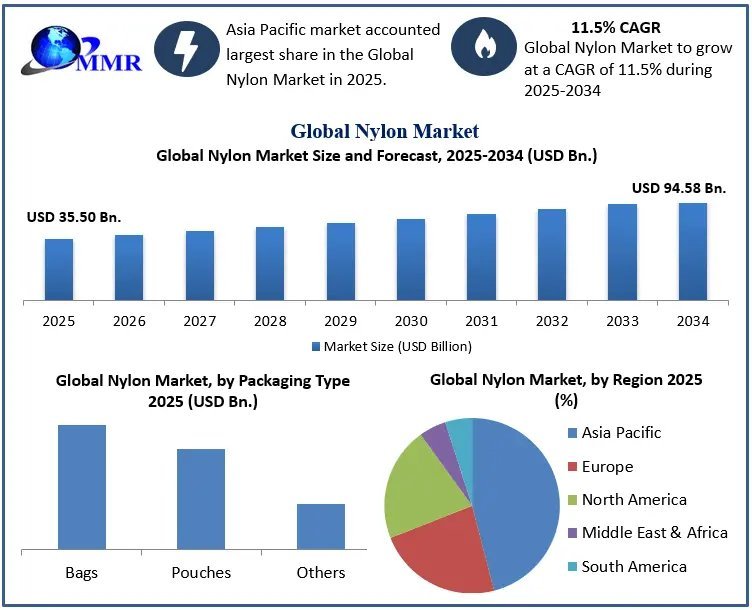
The Nylon Market was valued at USD 35.50 billion in 2025 and is projected to grow at a compound annual growth rate (CAGR) of 11.5% during the forecast period, reaching approximately USD 94.56 billion by 2034. Increasing demand for high-performance engineering plastics, durable synthetic fibers, and lightweight industrial materials is supporting market expansion across automotive, electrical and electronics, textiles, packaging, and industrial machinery applications.
Nylon, also known as polyamide, offers excellent mechanical strength, abrasion resistance, durability, and chemical resistance. These properties make it suitable for manufacturing automotive components, electrical connectors, industrial equipment, protective clothing, carpets, and flexible packaging materials. Manufacturers increasingly use nylon as an alternative to conventional metals and heavier materials to improve product performance and reduce component weight.
The automotive industry represents a significant growth opportunity as manufacturers seek lightweight materials that improve fuel efficiency and support electric vehicle development. Nylon components are increasingly used in engine compartments, battery systems, connectors, under-the-hood applications, and structural components. Meanwhile, growing demand for consumer electronics, industrial automation, and high-performance textiles is creating additional opportunities for nylon producers.
Sustainability is another important market driver. Investments in recycled polyamides, bio-based feedstocks, and lower-carbon manufacturing technologies are encouraging manufacturers to develop environmentally responsible materials. However, fluctuations in raw material prices, energy costs, and environmental compliance requirements may affect production economics. Companies investing in advanced manufacturing, material innovation, and recycling technologies are well positioned to capitalize on emerging opportunities.
Get Your Free Sample Report Link : https://www.maximizemarketresearch.com/request-sample/100350/
United States Market Trends and Investment Outlook
The United States nylon market is benefiting from demand for advanced engineering plastics, automotive components, industrial textiles, and sustainable polymer solutions. In February 2025, INVISTA announced progress in nylon 6,6 recycling technology through newly granted and filed patents aimed at improving access to recycled feedstocks, including technologies supporting post-consumer recycled content. In August 2025, INVISTA also highlighted plans to invest more than USD 500 million over five years across its operations, supporting its nylon fiber portfolio and performance textile businesses. Additionally, in October 2025, BASF expanded its North American sustainable polyamide 6 portfolio with Ultramid LowPCF and Ultramid BMB, offering lower-carbon-footprint alternatives. These developments demonstrate increasing investment in recycling, sustainable materials, and high-performance nylon solutions, creating opportunities across American manufacturing and industrial supply chains.
Nylon Market Segmentation: Largest Market Shares
By Product Type: Nylon 6 dominated the global market in 2025, accounting for more than 56% of total sales. Its competitive cost, mechanical strength, surface finish, and versatility support widespread adoption in automotive components, electrical protection devices, textiles, and industrial applications. Its suitability for reinforced engineering plastics further strengthens demand.
By Application: Automotive was the leading application segment in 2025, representing more than 36% of global sales. Demand is supported by vehicle lightweighting, durable component requirements, and the growing use of engineered polymers in conventional and electric vehicles. Nylon’s resistance to wear and mechanical stress makes it suitable for various interior, exterior, and under-the-hood components.
Competitive Analysis: Leading Companies and Strategic Developments
The global nylon industry features established chemical manufacturers and polymer specialists competing through production capabilities, product quality, technological development, and sustainability initiatives. Five prominent companies identified in the market report are:
- BASF SE: BASF develops engineering plastics and polyamide materials for automotive, electronics, and industrial applications. In March 2025, the company started commercial production at its Shanghai loopamid facility, with an annual capacity of 500 metric tons, supporting textile-to-textile recycling of polyamide 6. Its October 2025 North American launches of lower-carbon-footprint nylon 6 products further demonstrate its sustainability strategy.
- DuPont: DuPont supplies high-performance materials for electronics, transportation, and industrial applications. Its engineering materials expertise supports demand for lightweight, durable polymer solutions. Continued development of specialized materials and manufacturing technologies can help address evolving performance and reliability requirements.
- Nylon Corporation of America Inc.: The company participates in the nylon value chain, serving applications requiring dependable polymer and fiber solutions. Product development, operational efficiency, and responsiveness to industrial customer requirements remain important competitive priorities.
- Shenma Industrial: Shenma Industrial is an established Chinese nylon producer with exposure to nylon fibers, engineering plastics, and related materials. Its manufacturing capabilities and position within China’s industrial supply chain provide opportunities to serve growing domestic and international demand.
- DSM: DSM has a strong historical presence in engineering materials and polyamide technologies. Its legacy materials expertise supports applications requiring strength, durability, and specialized performance. Continued innovation across advanced polymers and sustainable material solutions remains relevant to the competitive landscape.
Other significant participants include LANXESS AG, Huntsman Corporation, AdvanSix Inc., UBE Industries Ltd., DOMO Chemicals, Toray Industries Inc., Ascend Performance Materials LLC, Toyobo Co. Ltd., Ashley Polymers Inc., and Goodfellow Group.
Regional Analysis: United States, Germany, France, United Kingdom, Japan, and China
China: China benefits from extensive chemical manufacturing infrastructure, strong textile production, and demand from automotive and electronics industries. Government priorities supporting advanced manufacturing, industrial upgrading, and resource recycling create opportunities for more efficient and sustainable nylon production. BASF’s commercial loopamid facility in Shanghai, launched in March 2025, highlights investment in recycled polyamide technology.
United States: Demand is supported by automotive manufacturing, industrial applications, electrical equipment, and performance textiles. Recycling innovation and investment in lower-carbon polymers are creating additional growth opportunities.
Germany: Germany’s automotive engineering industry and advanced manufacturing base support demand for durable, lightweight engineering plastics. Vehicle electrification and industrial efficiency initiatives provide opportunities for specialized nylon materials.
France: Automotive manufacturing, aerospace-related applications, technical textiles, and packaging contribute to nylon demand. Greater emphasis on circular materials and improved product sustainability encourages innovation in recycled polyamides.
United Kingdom: Demand arises from automotive supply chains, technical textiles, electrical equipment, and industrial manufacturing. Sustainability initiatives and interest in recyclable materials create opportunities for innovative nylon solutions.
Japan: Japan’s advanced automotive, electronics, and precision manufacturing industries support demand for high-performance nylon. Research into lightweight engineering plastics, material efficiency, and recycling technologies strengthens long-term market opportunities.
The report identifies Asia Pacific as the largest regional market in 2025, accounting for more than 43% of global sales. Individual country-level market shares for the six countries discussed above are not separately specified in the referenced market estimates.
Key Players
BASF SE, DuPont, Nylon Corporation of America Inc., Shenma Industrial, DSM, LANXESS AG, Huntsman Corporation, AdvanSix Inc., UBE Industries Ltd., DOMO Chemicals, Toray Industries Inc., Ashley Polymers Inc., Ascend Performance Materials LLC, Toyobo Co. Ltd., and Goodfellow Group.
Why This Market Matters Now
The nylon market is becoming increasingly important as industries prioritize lightweight components, manufacturing efficiency, material durability, and sustainability. Automotive electrification, expanding electronics production, and demand for advanced textiles are creating new applications for engineering-grade polyamides. Meanwhile, recycling technologies and lower-carbon production methods are opening opportunities for manufacturers to differentiate their products and strengthen supply-chain resilience.
For investors, manufacturers, suppliers, and procurement professionals, understanding market trends, competitive strategies, and regional demand is essential for identifying emerging opportunities. Companies that combine product innovation, cost-effective production, and sustainable material development can strengthen their competitive positions through 2034.